Capital Gains Tax Spain When Selling Property (2026): 19% for Non-Residents, the 3% Withholding and Plusvalía
· 12 November 2026
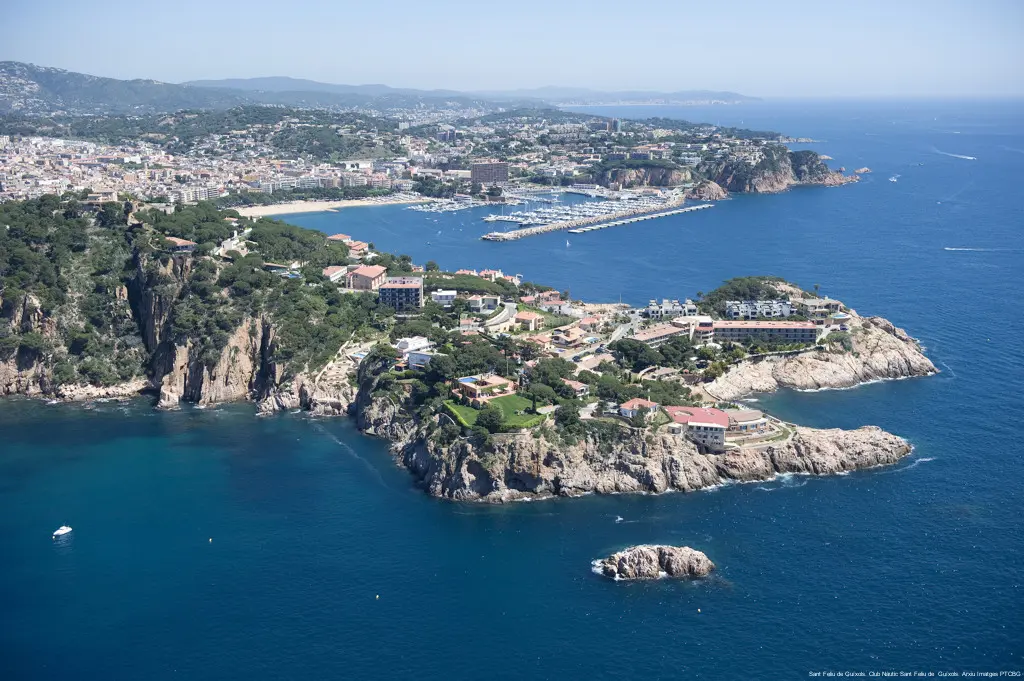
Capital gains tax in Spain for a non-resident who sells a home is a flat 19% of the gain, and the buyer holds back 3% of the price at the notary and pays it to the Spanish tax office as an advance on that tax. A seller who is resident in Spain pays 19% to 30% on the gain, in bands. The town hall then charges its own tax on the rise in land value, the plusvalía municipal, at a rate of up to 30%: in Lloret de Mar and Blanes the rate is exactly 30%.
Here is an example, with every assumption stated. A seller who lives in the UK sells a flat in Lloret de Mar for €300,000. She bought it in 2017 for €200,000 and paid €20,000 in purchase costs (tax, notary and Land Registry: our assumption). She never let it out, and to keep the sums simple we count no costs on the sale.
At the notary, the buyer keeps back 3% of the price, €9,000, and pays it to the tax office on form 211 within a month. Her gain is €300,000 minus €220,000, so €80,000, and the tax at 19% is €15,200. She files form 210 and pays the difference, €6,200. If her total purchase cost had been €270,000, the gain would be €30,000, the tax €5,700, and she would claim back €3,300 of the €9,000. Lloret's plusvalía is a separate bill on the land. Because she is not resident, the law makes the buyer pay it in her place, so the contract should say how that amount is settled between them.
This article is general information as of 12 November 2026. Check with your own tax adviser how the rules apply to your sale.
Capital gains tax in Spain for non-residents: 19% and the 3% withholding
Non-residents pay Spanish non-resident income tax (IRNR) on the gain from selling a property in Spain. The rate is 19%, the same for residents of the EU and of any other country.
The 3% the buyer keeps back. When the seller is not resident, the buyer withholds 3% of the agreed price and pays it to the Agencia Tributaria on form 211 within one month of the sale. This money is the seller's: it is an advance payment on the seller's own tax, and anything above the final tax is refunded.
Form 210, the seller's own return. The seller then declares the gain on form 210. The deadline is three months after the end of the buyer's one-month period. If the 3% is more than the tax due, the return asking for the refund can be filed from 1 February of the year after the sale, and within four years.
A loss. If there is no gain, there is no tax, and the whole 3% can be claimed back on form 210 under the same rule.
How the gain is worked out
- What you paid. The purchase price, plus improvements, plus the notary, Land Registry and agency costs of the purchase, plus the purchase taxes you paid (transfer tax, stamp duty or VAT). Keep the invoices: you'll need them.
- What you received. The sale price, minus the costs you pay as seller.
- If the home was let. Depreciation is subtracted from what you paid. If the home was rented out, the minimum depreciation is subtracted even if you never claimed it, which makes the gain larger.
- Homes bought before 1995. For a home bought on or before 31 December 1994, the part of the gain that arose up to 19 January 2006 is reduced by 11.11% for each year of ownership beyond two, counting years up to 31 December 1996 and rounding up. The reduction applies until the seller's total sales since 1 January 2015 reach €400,000. It exists in both resident and non-resident tax law.
Selling property in Spain as a non-resident: UK, EU and other countries
Sellers who live in the UK. Since Brexit the UK is not on the Spanish tax office's list of EU and EEA countries, so the reinvestment exemption described below is not available, and the gain is taxed at 19%. Under the UK-Spain double tax treaty, in force since 12 June 2014, Spain may tax gains on property in Spain, and the UK gives credit for the Spanish tax. How the UK then taxes the same gain is a question for a UK adviser.
Sellers who live in the EU or EEA. Residents of another EU country, Iceland, Norway or Liechtenstein can use the main home reinvestment exemption: if the home sold was their main home and they put the whole sale price into a new main home within two years before or after the sale, the gain is exempt. A partial reinvestment exempts the same share of the gain. The tax office page dates this possibility from 1 January 2015.
Over 65. The exemption for sellers over 65 who sell their main home is for Spanish residents only. The Ministry of Finance's rulings body (Dirección General de Tributos, ruling V2530-25 of 18 December 2025) has confirmed that it does not extend to non-residents, EU residents included.
Other countries. Spain applies the same 19% to a seller who lives in Ukraine, Russia or anywhere else. We haven't checked Spain's treaties with those countries, so how the gain is treated there is for your local adviser.
Capital gains tax for Spanish residents: 19% to 30%
A seller resident in Spain declares the gain in the annual income tax return (IRPF), in the savings part of the return. The bands below apply across Spain since 2025. Half of each rate goes to the State and half to the region, and Catalonia has no scale of its own for this part.
| Gain | Rate | State part | Regional part |
|---|---|---|---|
| Up to €6,000 | 19% | 9.5% | 9.5% |
| €6,000 to €50,000 | 21% | 10.5% | 10.5% |
| €50,000 to €200,000 | 23% | 11.5% | 11.5% |
| €200,000 to €300,000 | 27% | 13.5% | 13.5% |
| Over €300,000 | 30% | 15% | 15% |
Each rate applies only to the slice of the gain inside its band. Residents have three exemptions that matter on a home sale:
- Reinvesting in a new main home. Put the whole sale price into a new main home within two years before or after the sale and the gain is exempt; reinvest part and that share of the gain is exempt. A main home means one you have lived in for at least three years, and it still counts if it was your main home at the sale or on any day in the two years before.
- Over 65. A seller over 65 pays no tax on the gain from selling their main home.
- Handing the home to the bank. The gain is exempt when the main home goes to the lender to pay off a mortgage owed to a bank or other credit institution (dación en pago).
Residents don't have the 3% withheld: that rule applies only to non-resident sellers.
Plusvalía tax in Spain: the town hall's tax on the land
The plusvalía municipal (officially IIVTNU) taxes the rise in value of the land under the home while you owned it. It is a local tax, separate from the income tax on the gain.
Who pays. The seller. When the seller is a non-resident individual, the law makes the buyer pay it as the seller's substitute.
Two ways to calculate it. Under the objective method, the cadastral value of the land is multiplied by a coefficient that depends on how many years you owned the home, and the town's rate is applied to the result. Under the real-gain method, the tax is based on the actual increase. The taxpayer chooses the real gain when it gives a lower figure. If there was no increase at all, there is no tax. These rules date from November 2021, after rulings of the Constitutional Court.
Rate and deadline. The town sets the rate, up to 30%. The return is due within 30 working days of the sale (six months, extendable to a year, after a death).
Lloret de Mar and Blanes. Both charge 30%. Lloret's 2026 tax ordinance has its own coefficients, for example 0.15 for nine years and 0.40 for twenty years or more, with 30 working days to declare. Blanes uses the legal maximum coefficients.
New coefficients from 1 December 2026. Royal Decree-Law 29/2026, in force since 8 October 2026, sets new maximum coefficients from 1 December 2026, listed below. Where a town's ordinance has a higher coefficient, the legal maximum applies: in Lloret, a home owned for twenty years or more would use a coefficient of 0.30 instead of the ordinance's 0.40, while for nine years the ordinance's 0.15 stays below the maximum of 0.25. As an illustration only, with an assumed cadastral land value of €60,000, a Lloret flat owned for nine years and sold after 1 December gives a base of €9,000 and a tax of €2,700 at 30%. The same decree-law also adds an income tax exemption for Spanish residents (IRPF) on sales to a public housing body between 8 October 2026 and 31 December 2027, when the price is under €800,000 and the home has stood empty for two years without a justified reason. Decree-laws must be validated by Congress, so check the status before you sign.
| Years owned | Maximum coefficient |
|---|---|
| Less than 1 | 0.17 |
| 1 and 2 | 0.16 |
| 3 and 4 | 0.17 |
| 5 | 0.19 |
| 6 | 0.21 |
| 7 | 0.23 |
| 8 | 0.24 |
| 9 | 0.25 |
| 10 | 0.22 |
| 11 | 0.18 |
| 12 | 0.14 |
| 13 | 0.12 |
| 14 to 17 | 0.11 |
| 18 | 0.13 |
| 19 | 0.20 |
| 20 or more | 0.30 |
Other seller costs and documents in Catalonia
- Notary and Land Registry. Under Catalan civil law, unless the parties agree otherwise, the buyer pays for the deed, the first copy and what comes after it, and the seller pays the costs of delivering the property.
- Community of owners certificate. The seller declares that there are no community debts and brings a certificate from the community secretary. Without it the deed isn't signed unless both sides waive it. The property itself is liable for unpaid fees of the current year and the four before, which is why buyers insist on it.
- Cèdula d'habitabilitat. Catalonia's certificate that the home is fit to live in is needed to sell. For a resale home it lasts 15 years, for a new build 25.
- Energy certificate. The seller provides it. It is valid once registered with the Catalan energy institute (ICAEN), for 10 years, or 5 years for a G rating.
- IBI. The annual property tax falls on whoever owns the home on 1 January, for the whole year. The seller can pass part of that cost to the buyer under civil law, so agree it in the contract.
If the home is let to a tenant, the new rental rules may affect the sale. Get a lawyer's advice on that before you put it on the market.
For the yearly taxes a non-resident owner pays while keeping a home in Spain, see our article on Spanish property tax for non-residents. If you're selling to buy again, our purchase tax calculator for Catalonia shows what the next purchase will cost in tax.
Three practical rules
1. Gather your purchase papers before you set a price. The purchase deed, the tax receipts and the invoices for improvements decide the size of your gain. Without them you may pay 19% on money you have already spent.
2. Ask for the plusvalía figure early. Get the cadastral land value from your IBI receipt and work out both methods, or have your adviser do it. If you're not resident, agree with the buyer in the contract how it is paid.
3. Diary the form 210 dates. To pay, file within three months after the buyer's one-month deadline; to claim a refund, file from 1 February of the next year, within four years. The refund has to be claimed on that form.
Questions people ask
What is capital gains tax in Spain for non-residents?
A non-resident who sells a property in Spain pays 19% non-resident income tax on the gain, whether they live in the EU, the UK or elsewhere. The buyer withholds 3% of the price and pays it on form 211 within a month; the seller then files form 210, paying the difference or claiming back any excess.
What is the 3% retention when selling property in Spain?
When the seller is not resident in Spain, the buyer keeps back 3% of the price and pays it to the Spanish tax office within one month. It is an advance on the seller's capital gains tax: if the final tax is lower, the seller claims the difference back on form 210.
Do I pay capital gains tax in both Spain and the UK?
Under the UK-Spain double tax treaty, in force since 12 June 2014, Spain may tax a gain on property in Spain and the UK gives credit for the Spanish tax. Ask a UK adviser how the UK side works for you. As the UK is not in the EU or EEA, UK residents can't use Spain's main home reinvestment exemption.
Who pays the plusvalía tax in Spain?
The seller pays the plusvalía municipal. If the seller is a non-resident individual, the law makes the buyer pay it as the seller's substitute. The rate is set by each town, up to 30% (Lloret de Mar and Blanes charge 30%), and there is no tax if the land did not rise in value.
What capital gains tax do Spanish residents pay when they sell a home?
Residents pay 19% on the first €6,000 of gain, 21% up to €50,000, 23% up to €200,000, 27% up to €300,000 and 30% above. The gain can be exempt if the seller reinvests in a new main home within two years, is over 65 and sells their main home, or hands the main home to the bank to clear the mortgage.
Thinking of selling a home on the Costa Brava?
Tell us the town, the type of home and when you bought it. We'll give you a realistic view of the price and a checklist of the documents you'll need, and if you'd like, we can put you in touch with a tax adviser.
 Author: @katy.bon.estate, property consultant on the Costa Brava
Sources: Agencia Tributaria, Manual Renta 2025, savings rates, Manual for non-residents (gains on property sales, exempt income) and form 210 and deadlines; Ley 35/2006 (IRPF), arts. 33, 38, 66 and 76; Ley 7/2024; Real Decreto 439/2007 (IRPF regulation), arts. 41 and 41 bis; Real Decreto Legislativo 5/2004 (non-resident income tax), art. 25.2 and additional provision 7; Real Decreto 1776/2004, art. 14; Dirección General de Tributos, ruling V2530-25; UK-Spain double tax convention; Real Decreto Legislativo 2/2004 (local taxes), arts. 63, 75, 104 to 110; Real Decreto-ley 26/2021; Real Decreto-ley 29/2026, art. 10; Ajuntament de Lloret de Mar, tax ordinance 5 for 2026; Ajuntament de Blanes, tax ordinances 2026; Codi civil de Catalunya, arts. 531-6, 553-5 and 621-15; Decret 141/2012 (cèdula d'habitabilitat); Real Decreto 390/2021 (energy certificate). Information as of 12 November 2026.